
SSL Encrypted Licensed Agents Free Service
Quiet Florida beach with a lifeguard stand and calm surf

Florida · term and permanent life

Life insurance
for Florida households.

Help sizing and comparing term and permanent life coverage, in states where we are licensed for life insurance. We start with who depends on you, then look at options.

Why people call us

A paycheck, a mortgage,
people who count on you.

Most people start thinking about life coverage after something changes. Three moments we hear about often:

We just bought a house.

A 30-year loan is a long promise. Some owners choose a term length that runs about as long as the loan, so the balance is not left to a spouse.

I work for myself.

There is no group policy at work to lean on. Your coverage is whatever you set up yourself, so the amount matters more.

Our first baby is on the way.

Children bring years of costs, from day care to college. Many parents look at coverage before the due date, while they are thinking about it.
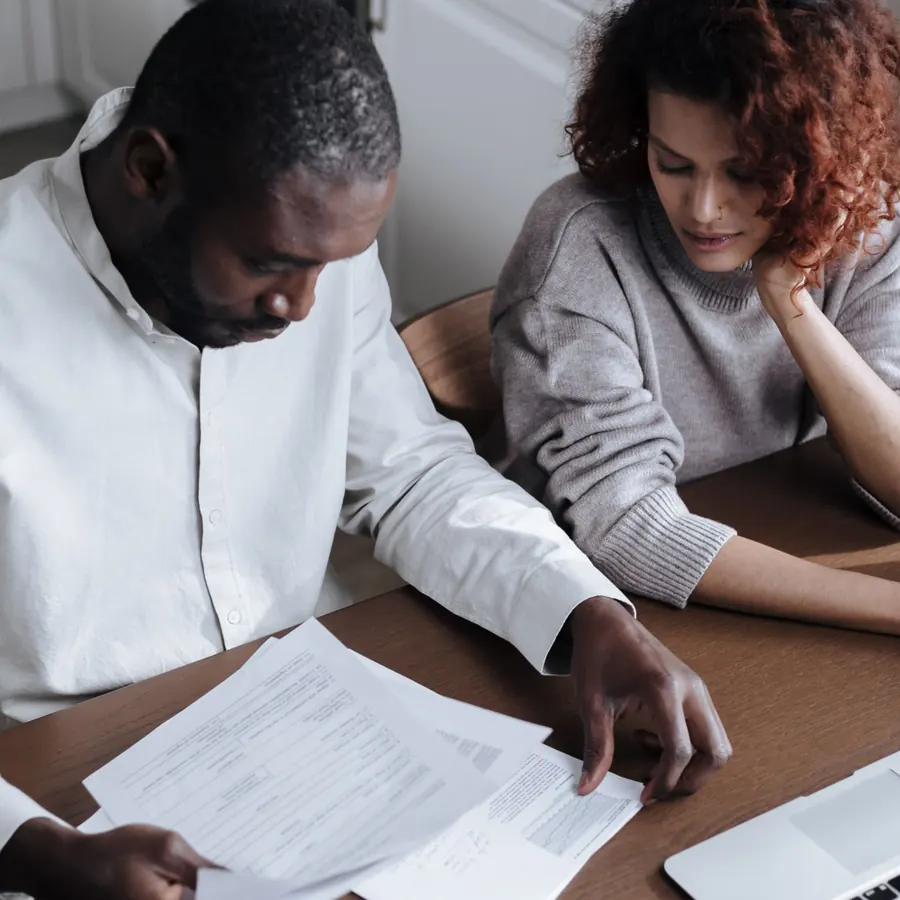
Couple reading insurance papers together at a kitchen table

Two main types

Term and permanent,
in one minute.

Life insurance pays money to the people you name if you die while the policy is in force.

  • Term life covers you for a set number of years, such as 10, 20, or 30. If the term ends, the coverage ends unless the policy lets you renew or convert it.
  • Permanent life, like whole life or universal life, is built to last for life as long as you pay what the policy requires. It usually costs more for the same amount.
  • Some permanent policies build cash value. It grows slowly, has fees, and loans or withdrawals lower what your family receives.
  • Every policy is approval-based. The insurance company looks at your age, health, habits, and sometimes your income before it decides.
  • Read more in our term vs whole life guide.
  • Business owners: see key person life insurance and buy-sell agreement life insurance.
Paul Daniels
Paul DanielsLicensed insurance agent · NPN 20986580

How we help

An independent brokerage, not one company.

We are not tied to a single insurance company. We ask what the money needs to do, how long it needs to last, and what fits your budget. Then we request quotes from companies we are appointed with and walk you through them.

Many of our clients first came to us for health insurance. Life coverage is a separate product with its own application, so we handle it as its own conversation.

  • No pressure and no obligation to buy
  • Life insurance in states where we are licensed for life insurance · Paul Daniels, NPN 20986580 · FL license G065122
  • No fee for our help. If you buy, the insurance company pays us a commission, and commissions can differ by company.

Three steps

Florida life insurance, step by step.

Tell us who depends on you

Share your age, your household, your debts, and how many years your family would need help.

Compare options

We show term and permanent choices side by side, with what each would and would not do.

Apply when ready

The insurance company reviews your application and makes the final decision.

Straight answers

What we will not say.

Life insurance is a long-term contract. We would rather you buy the right amount slowly than the wrong amount fast.

  • We do not promise approval or a price.
  • We do not call any policy the cheapest or the best.
  • We do not push permanent coverage when term does the job.

Before you call

Five things to have handy.

  • A rough total of your debts, including the mortgage
  • Your yearly income, or two years of tax returns if you are self-employed
  • Any life coverage you already have, including through work
  • Your health history and current medicines
  • The names of the people you would want to receive the money

Questions

Florida life insurance FAQ.

As of October 13, 2026.

Who can buy life insurance through Daniels Health Advisors?

We help people buy term and permanent life insurance in states where we are licensed for life insurance. Florida residents are our main focus. Every policy depends on approval by the insurance company.

How much life insurance do I need?

There is no single rule. Add up debts, years of income your family would need, and future costs like college. Then subtract savings and any coverage you already have. We can walk through the math with you.

Is term or whole life better?

Neither is better for everyone. Term covers a set number of years and usually costs less for the same amount. Whole life is built to last for life and costs more. The right fit depends on what the money needs to do.

Do I need a medical exam?

Some policies ask for an exam and lab work. Others decide using health questions and records. Policies with no exam may cost more or have lower limits. Approval is never guaranteed.

Is a life insurance payout taxed?

In general, the death benefit paid to a beneficiary is not counted as income for federal tax. There are exceptions, such as interest added to a payout. Ask your CPA about your own case.

Do you also help with health insurance?

Yes. We help with health insurance too. Life and health coverage are separate products with separate applications.

Let us size it
with you.

Book a free 15-minute call, and we will start with who depends on you.

Disclaimer

Daniels Health Advisors LLC is an independent insurance brokerage, not an insurance company. Agent: Paul Daniels, NPN 20986580, Florida license G065122. We help with life insurance only in states where we are licensed for life insurance. Life insurance is not health insurance. Every policy depends on approval by the insurance company, based on things like age, health, habits, and income. Prices and terms are set by the insurance company. We never guarantee approval or a price, and we do not promise any company's rates. Cash value, loans, and riders work differently in each policy. This page is general information, not legal or tax advice. Talk with your CPA or attorney about tax and legal questions.