“I’ve know Paul for years and definitely trust him in the health advisor dept! Working with small business owners he has been a great partner with explain options and provide solutions!”
Sandra D.
Facebook recommendation
Facebook recommendation


For people leaving a spouse's plan · Licensed in 20 U.S. states
If you were on your spouse's plan, the divorce or separation can end that coverage on a date you don't control. Here is how to line up a plan in your own name before that date arrives.
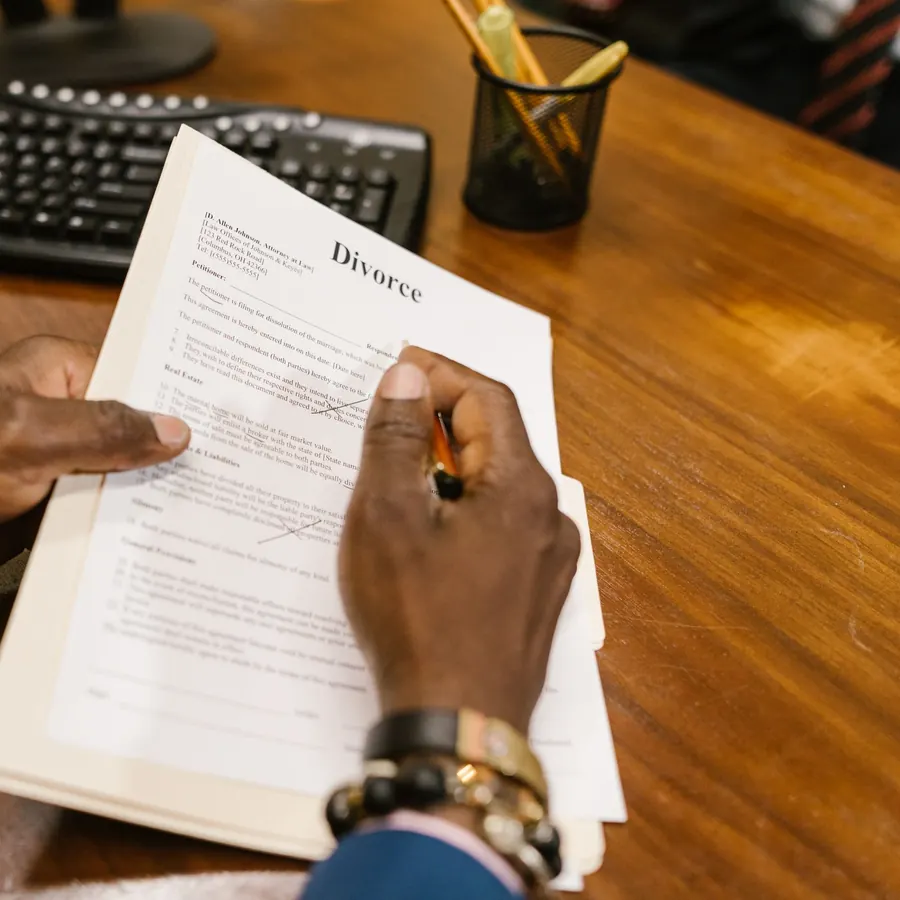
Photo: Pexels photo 4245977 by Ketut Subiyanto, used under the Pexels License. Cropped, resized, and converted to WebP. Modified from the original.
Starting over
The CDC counted 672,502 divorces in 2023 in the 45 states and D.C. that report them (provisional data). If you were covered through your spouse, three points matter most:
HealthCare.gov lists divorce or legal separation as a reason for a special enrollment period only if you lose health coverage. If you keep your coverage, the divorce by itself doesn't qualify you.
A loss of coverage can qualify you if it happened in the past 60 days, or if you expect it in the next 60 days. Applying early can help you avoid a gap between the old plan and the new one.
Marketplace savings follow the income you expect for the year. Moving from two incomes to one may mean a larger tax credit, within the income limits.
Your new household
The Marketplace bases tax credits on your household income for the year you are covered.
Divorce in numbers
Of separated U.S. adults ages 19 to 64 had no health insurance in 2025.
Of divorced U.S. adults ages 19 to 64 had no health insurance in 2025.
Of married U.S. adults ages 19 to 64 had no health insurance in 2025.
Source: U.S. Census Bureau, Health Insurance Coverage in the United States: 2025 (P60-291) (rates by marital status, adults 19 to 64), published September 15, 2026. A person counts as uninsured only if they had no coverage at all in 2025. Nationwide data.
Working with Paul
Daniels Health Advisors is the independent brokerage Paul Daniels founded, licensed in 20 U.S. states. We help people coming off a spouse's job plan or a shared family plan find coverage in their own name. We often begin with the Marketplace, because a single paycheck can qualify for a tax credit. When no credit is likely, we look at private PPO options too. Some private plans ask health questions, and approval is not guaranteed. Some may not cover care for health problems you had before you enrolled.
We only need dates, income, and who you will claim. The rest of your divorce stays your business.
Your first call
When the decree is final or expected, and the day your spouse's plan will stop covering you.
Who you will claim this year, and the income you expect on your own.
Each choice laid out on one page, and every doctor you see looked up in the network.
Recommended on Facebook
“I’ve know Paul for years and definitely trust him in the health advisor dept! Working with small business owners he has been a great partner with explain options and provide solutions!”
“Paul was very helpful in my search for business group insurance. He was able to explain my options and answer all the questions I had before signing up. Highly recommend working with him!”
Before the decree
Ask your spouse's plan for the exact date your coverage ends, then aim for a new plan that starts the next day. If you shared a Marketplace plan during the year of the divorce, the IRS Form 8962 instructions explain how to split the plan's amounts with a former spouse at tax time, so talk to a tax pro. If you take advance credits and earn more than you estimated, part of the credit may have to be repaid. Under current law, starting with 2026 taxes, there is no cap on that payback. By the end of the call you will have:
A checklist for
Divorce questions
Only if you lose health coverage because of it. HealthCare.gov says divorce or legal separation without losing coverage doesn't qualify. If you will lose coverage, you can apply up to 60 days before it ends, or within 60 days after.
Sometimes, for a while. Federal continuation coverage rules can let a former spouse keep the same group plan for up to 36 months after a divorce or legal separation, if the employer has 20 or more employees. You generally must tell the plan within 60 days, and the plan may charge up to 102% of the cost. Compare that price with a plan of your own.
If you are still legally married, include your spouse, even if you live apart, unless you are legally separated. Most married couples must file jointly to get savings. Some spouses who live apart can file as head of household, and victims of domestic abuse or abandonment can say they are unmarried.
Child support doesn't. Alimony counts only if the divorce or separation was finalized before January 1, 2019. Alimony from later agreements doesn't count on a Marketplace application.
Often, yes. Children can usually stay on a parent's plan until age 26 if the plan covers dependents. If you add them to your own Marketplace plan instead, include them in the years you claim them as tax dependents.
Not for every plan. A private plan (not from the Marketplace) can often be bought any time of year. Some private plans ask health questions, and approval is not guaranteed. Some may not cover care for health problems you had before you enrolled. Marketplace plans, and other plans that follow ACA rules, work differently. As of October 24, 2026, under current law, open enrollment for 2027 plans on HealthCare.gov runs from November 1, 2026, to January 15, 2027. To start coverage January 1, pick a plan by December 15. States that run their own Marketplace may set different dates, so check with your state's Marketplace. A federal appeal about these rules is pending (City of Columbus v. Kennedy, 4th Cir. No. 26-1938), with oral argument set for October 30, 2026, so confirm the dates before you enroll. Outside open enrollment, you need a special enrollment period, such as one after losing job-based coverage.
Pick a 15-minute slot that suits you, or get prices online first.
Daniels Health Advisors LLC is an independent brokerage, not a carrier, HealthCare.gov, or CMS. Agent: Paul Daniels, NPN 20986580, Florida license G065122. This page is about personal health insurance after a divorce or legal separation. It is not tax or legal advice. Coverage figures are from public government data and describe groups, not you. Tax credits, plans, networks, and prices depend on your state, zip code, income, and household. We never guarantee approval, a doctor, or a price. Not medical, legal, or tax advice.