“I’ve know Paul for years and definitely trust him in the health advisor dept! Working with small business owners he has been a great partner with explain options and provide solutions!”
Sandra D.
Facebook recommendation
Facebook recommendation


For Floridians under 30 and others who qualify · Licensed in 30+ U.S. states
A catastrophic plan is an ACA plan with a very high deductible. Premiums vary by plan. It is built for the worst-case year, and not everyone can buy one.
Top photo: Pexels photo 6578430 by Andres Ayrton, used under the Pexels License. Cropped, resized, and converted to WebP. Modified from the original.
Built for big bills
A catastrophic plan is still an ACA plan, with the same core protections. Three things young Floridians ask us first:
Covered preventive care at no cost to you, plus at least three primary care visits a year. For most other care, you pay until you reach the deductible.
Under current rules, it equals the ACA's yearly out-of-pocket limit. For 2027, that limit is $12,000 for one person.
No. Federal tax law leaves catastrophic plans out of the premium tax credit. If you qualify for a credit, a bronze or silver plan may cost you less.
Who can buy one
Federal rules limit these plans to two groups of people.
Across a plan year
Covered preventive care costs you nothing, and at least three primary care visits are covered before the deductible. Check your plan for any copay.
Once you reach the deductible, which is also your out-of-pocket limit, the plan pays for covered in-network care for the rest of the plan year.
Starting in 2026, IRS rules treat catastrophic plans available through the Marketplace as HSA-eligible. Other HSA rules still apply, so check with your tax pro.
Catastrophic plans in Florida
Floridians picked a catastrophic plan for 2026.
of the 4,538,772 Marketplace plan selections in Florida.
Floridians picked a bronze plan, the lowest metal level.
Source: CMS 2026 Marketplace Open Enrollment public use files (Florida, plan selections from November 1, 2025, to January 15, 2026). The under 0.1% is our math: 3,437 of 4,538,772, or 0.08%. Counts, not a recommendation.
Working with Paul
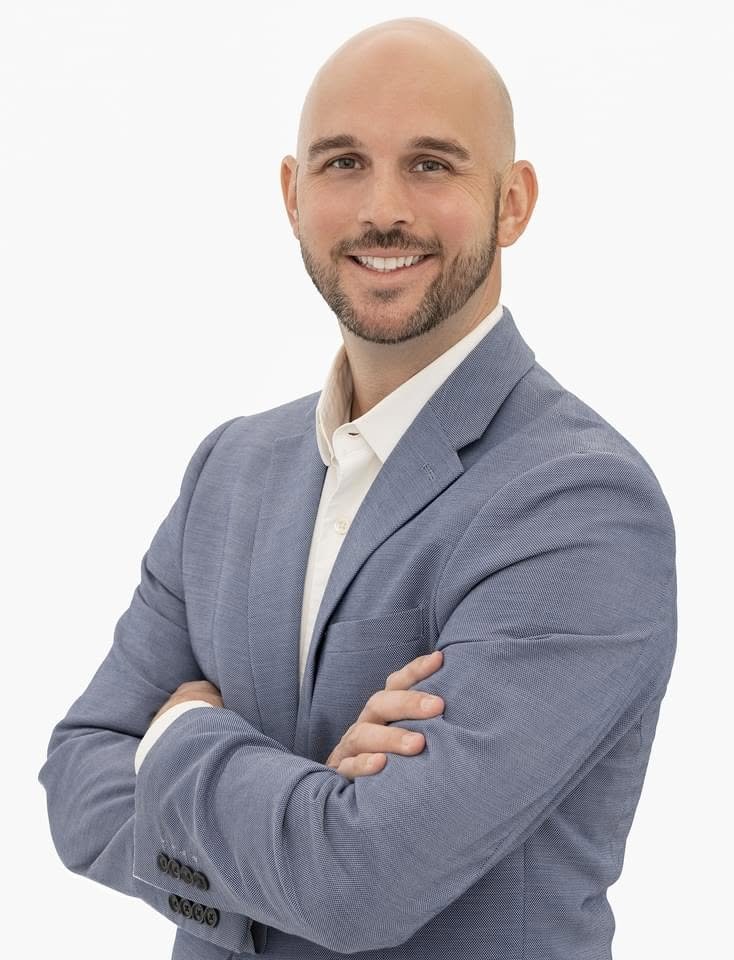
Paul Daniels owns Daniels Health Advisors, an independent brokerage licensed in 30+ U.S. states. Young Floridians, students, and people just starting out call us when they want the smallest premium and aren't sure what they give up. We check whether you qualify, price a catastrophic plan next to bronze and silver after any tax credit, and help you enroll. If another ACA plan doesn't suit you, we can also show private PPO options. Some private plans ask health questions, and approval is not guaranteed. Some may not cover care for health problems you had before you enrolled.
Coming off a parent's plan? Our turning 26 guide walks through your choices.
Your first call
Birth dates, zip code, and a careful estimate of next year's income.
Catastrophic, bronze, and silver, each priced after any tax credit.
Pick your plan during open enrollment or a special enrollment period.
Recommended on Facebook
“I’ve know Paul for years and definitely trust him in the health advisor dept! Working with small business owners he has been a great partner with explain options and provide solutions!”
“Paul was very helpful in my search for business group insurance. He was able to explain my options and answer all the questions I had before signing up. Highly recommend working with him!”
Before you choose catastrophic
A catastrophic plan keeps the monthly bill down, but a single hospital stay could leave you owing up to the full deductible. Make sure you could cover that, or set money aside in an HSA if you are eligible. You will leave with:
A checklist for
Catastrophic plan questions
It is an ACA plan with a very high deductible, sold to people under 30 and to some people with an approved exemption. It covers preventive care and at least three primary care visits a year before the deductible.
People who are under 30 on the first day of the plan year qualify. If you are 30 or older, you usually need an approved exemption. It can be for hardship or because other plans cost too much for you. On a family plan, everyone covered must qualify.
No. The premium tax credit can't be used on a catastrophic plan. If you qualify for a credit, compare bronze and silver plans, which may cost less after the credit.
Yes. Like other ACA plans, it can't turn you down or refuse to cover care for a condition you already have. You still need to enroll during open enrollment or a special enrollment period.
Eligibility is based on your age on the first day of the plan year. If you turn 30 during the year, you can generally keep the plan until that plan year ends. After that, you need an exemption or a different plan.
For a private plan (not from the Marketplace), you can often apply any time of year. Some private plans ask health questions, and approval is not guaranteed. Some may not cover care for health problems you had before you enrolled. Marketplace plans, and other plans that follow ACA rules, work differently. As of October 17, 2026, under current law, open enrollment for 2027 plans runs from November 1, 2026, to January 15, 2027. A court case about these dates is still on appeal, so confirm the dates before you enroll. To start coverage January 1, pick a plan by December 15 (the deadline under current law). Outside those dates, you may need a special enrollment period. Losing job-based coverage is one example.
Book a free 15-minute call or start a quote online.
Daniels Health Advisors LLC is an independent brokerage, not a carrier, HealthCare.gov, or CMS. Agent: Paul Daniels, NPN 20986580, Florida license G065122. This page is about personal and family health insurance. It is not business liability or workers' comp insurance. We are not part of any union or trade group. Job and pay numbers are from public government data and describe groups of workers, not you. Tax credits, plans, networks, and prices depend on your state, zip code, income, and household. We never guarantee approval, a doctor, or a price. Not medical, legal, or tax advice.