“I’ve know Paul for years and definitely trust him in the health advisor dept! Working with small business owners he has been a great partner with explain options and provide solutions!”
Sandra D.
Facebook recommendation
Facebook recommendation


For anyone comparing health plans · Licensed in 20 U.S. states
A summary of benefits and coverage, or SBC, is a short, plain-language overview of what a health plan covers and what you pay. Every SBC uses the same federal format, so you can line up two plans and compare them section by section. Here's where to find one, what's on it, and how to read it before you enroll.
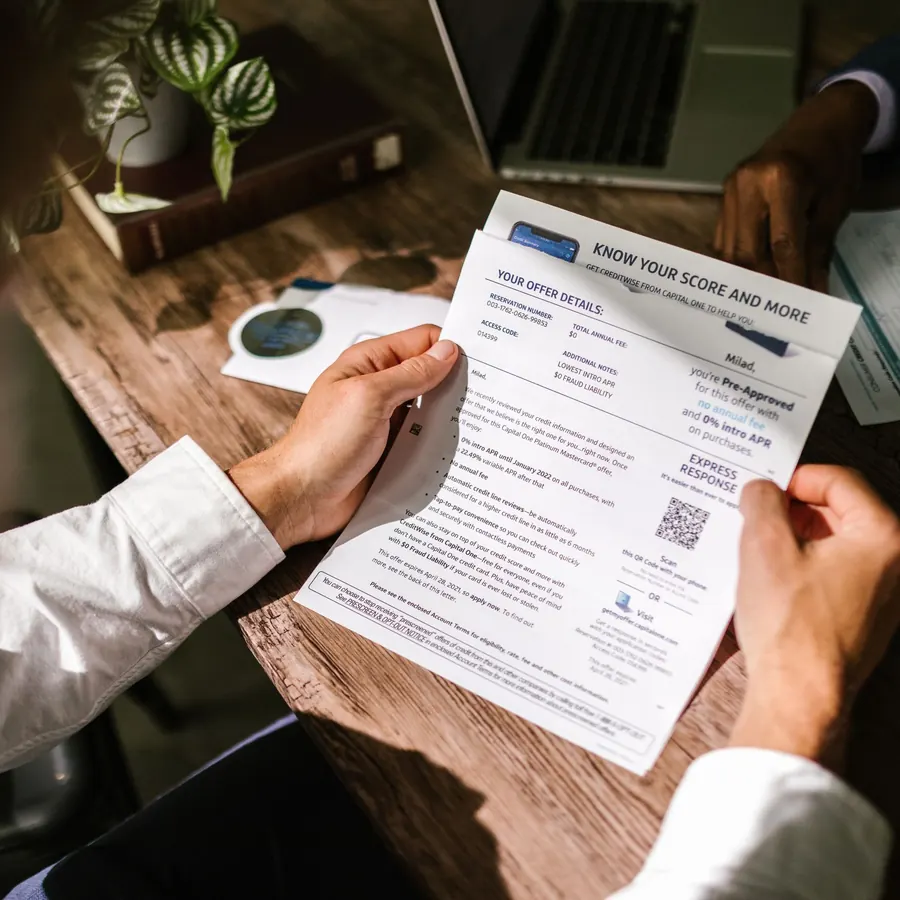
Photo: Pexels photo 6532609 by Budgeron Bach, used under the Pexels License. Cropped, resized, and converted to WebP. Modified from the original.
What an SBC is
HealthCare.gov and the federal SBC rules describe it this way:
You can get an SBC for all individual and job-based health plans, including grandfathered plans. It comes with a Uniform Glossary that defines common insurance terms.
On HealthCare.gov there is a link to the SBC on each plan page. You can also ask your insurer or employer plan for one at any time, and it must be free.
Each SBC must say that it is only a summary, and that the plan's policy or plan document sets the full terms of coverage.
What is on the form
These points summarize HealthCare.gov, Summary of Benefits and Coverage and 45 CFR 147.200, read November 1, 2026.
The format rules
The most an SBC can run, printed double-sided, in a font no smaller than 12 point.
How long an insurer has to send an SBC after you ask for one.
The advance notice required for a material change to a plan in the middle of a plan year, if it affects the SBC.
Figures from 45 CFR 147.200, read November 1, 2026. They apply to individual and group health coverage covered by that rule.
Working with Paul
Daniels Health Advisors is the independent brokerage Paul Daniels founded, licensed in 20 U.S. states. We pull the SBC for each plan you're considering and compare the lines that matter for your care, such as the deductible, the out-of-pocket limit, specialist visits, and drug costs, across Marketplace plans and, where they fit, private PPO options. Some private plans ask health questions, and approval is not guaranteed. Some may not cover care for health problems you had before you enrolled.
Bring a list of the care you use most, like doctor visits, prescriptions, or therapy. It tells us which SBC lines to compare first.
Your first call
Visits, prescriptions, and anything planned for next year.
One for every plan you are weighing.
Deductibles, copays, and limits side by side.
Recommended on Facebook
“I’ve know Paul for years and definitely trust him in the health advisor dept! Working with small business owners he has been a great partner with explain options and provide solutions!”
“Paul was very helpful in my search for business group insurance. He was able to explain my options and answer all the questions I had before signing up. Highly recommend working with him!”
Comparing plans
Since every SBC follows the same layout, compare them row by row: the deductible on one against the deductible on the next, then the out-of-pocket limit, then the copays for the care you use. If a plan you are considering doesn't come with an SBC, ask for its full plan documents before you enroll. After the call you will have:
A checklist for
SBC questions
A summary of benefits and coverage (SBC) is a short, plain-language summary of a health plan's benefits and costs. Every SBC uses the same format, which makes it easier to compare plans side by side.
On HealthCare.gov, there's a link to the SBC on each plan page when you preview plans and when you compare plans after you apply. You can also ask the insurer or your employer's plan for a copy at any time.
No. Federal rules say an SBC must be provided free of charge. If you ask for one, the insurer must send it within 7 business days.
They are sample situations, such as having a baby or managing diabetes, that show roughly what the plan would pay and what you would owe. They help you compare plans, but they are not cost estimates for your own care.
No. You get an SBC before or when you enroll, to understand a plan. An explanation of benefits comes after you get care, to show how the plan handled a claim.
Not for every plan. A private plan (not from the Marketplace) can often be bought any time of year. Some private plans ask health questions, and approval is not guaranteed. Some may not cover care for health problems you had before you enrolled. Marketplace plans, and other plans that follow ACA rules, work differently. As of November 1, 2026, under current law, open enrollment for 2027 plans on HealthCare.gov runs from November 1, 2026, to January 15, 2027. To start coverage January 1, pick a plan by December 15. States that run their own Marketplace may set different dates, so check with your state's Marketplace. A federal appeal about these rules is pending (City of Columbus v. Kennedy, 4th Cir. No. 26-1938; argued October 30, 2026, with no ruling as of November 1, 2026), so confirm the dates before you enroll. Outside open enrollment, you need a special enrollment period, such as one after losing job-based coverage.
Book a 15-minute call to go through the SBCs together, or see quotes online.
Daniels Health Advisors LLC is an independent brokerage, not a carrier, HealthCare.gov, or CMS. Agent: Paul Daniels, NPN 20986580, Florida license G065122. This page explains SBCs in general. Benefits and costs vary by plan, so read the SBC and the policy for the plan you are considering. These are federal rules for individual and group health coverage. Plans outside those rules may not provide an SBC. Tax credits, plans, networks, and prices depend on your state, zip code, income, and household. We never guarantee approval, a doctor, or a price. Not medical, legal, or tax advice.